· ReadyStack
Worked example
Real numbers from this tool, line by line.
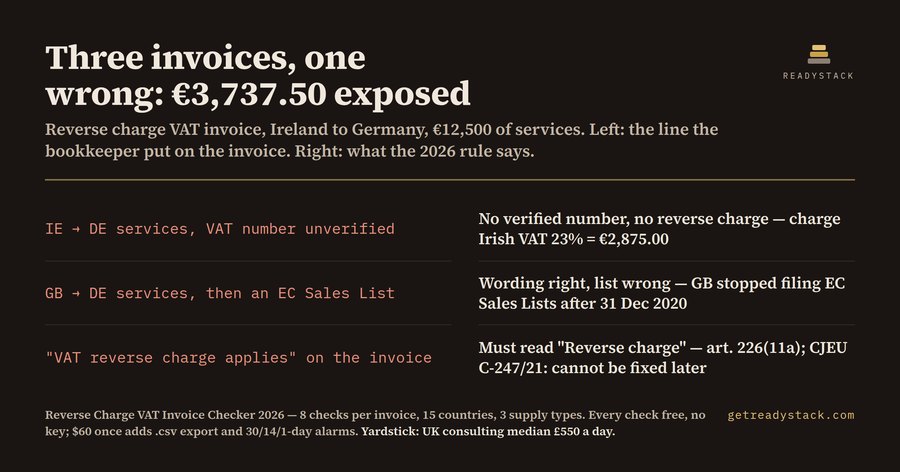
€3,737.50 of exposure sits on a single invoice — a Dublin bookkeeper, €12,500 of consultancy for a Berlin client, one box left unticked.
Here are the eight answers the checker printed for that invoice, before anyone explained anything:
| Who accounts for the VAT | You charge VAT — no verified VAT number, so there is no B2B reverse charge | | VAT you put on this invoice | €2,875.00 | | Wording that must appear on the invoice | Standard VAT invoice — never print "Reverse charge" without a VAT number verified on VIES | | Legal basis | An unverified customer is treated as non-taxable · charge Ireland VAT at 23% (art. 45 / VATA 1994 s.7A) | | EC Sales List | No — only supplies the customer self-accounts for go on an EC Sales List | | Invoice deadline | National rule | | Exposure if this call is wrong (VAT + 30% penalty) | €3,737.50 | | Time left to file | 63 days |
The invoice had already gone out carrying the words "Reverse charge". Tick the verified box and the same invoice comes back as €0.00, the words "Reverse charge", and a deadline of 15 Oct 2026. One box.
The wording was right. The problem was that nobody had checked the customer's VAT number on VIES. Without a verified number the customer is not a taxable person for this purpose, the B2B general rule in art. 44 does not apply, and the supply is Irish. €2,875.00 of Irish VAT at 23% should have been on the document. Because the reverse charge was claimed instead, the VAT is still due — from the supplier, not the customer — and a careless error carries a penalty of up to 30% of the tax under the Finance Act 2007 Schedule 24 standard. €2,875 plus 30% is €3,737.50, and it surfaces at the next return rather than on the day the invoice was raised.
That was one of three invoices raised that week, and the other two fail differently.
The second was £48,000 of groundworks between two UK contractors. UK construction between two VAT-registered businesses has been on the domestic reverse charge since 1 March 2021, and the invoice has to say so in terms: "Reverse charge: VAT Act 1994 Section 55A applies — customer to pay the VAT to HMRC". £0.00 of VAT is charged, and £12,480 is what is at stake if that call is wrong.
The third was €31,000 of retainer work from a German agency to a London client, and it is the one where a chatbot will confidently mislead you. A German supplier billing a UK business is right to reverse-charge — but it does not go on an EC Sales List, because the United Kingdom left the EU VAT area on 1 January 2021. Great Britain stopped filing EC Sales Lists after 31 December 2020 as well. Advice written before those dates, and models trained on it, still tell people to file one.
There is one more trap. Inside the EU, art. 226(11a) requires the literal words "Reverse charge" on the invoice. In Case C-247/21 the Court of Justice held that a different phrasing will not do and that the omission cannot be repaired by sending a correction afterwards. "VAT reverse charge applies" is not the same thing as "Reverse charge".
And the clock: for intra-EU reverse-charge supplies the invoice itself is due by the 15th day of the month following the supply (art. 222). A supply dated 30 September 2026 has to be invoiced by 15 October 2026.
The Reverse Charge VAT Invoice Checker is a browser extension that produces that table from what you are supplying, where you are registered, where the customer belongs, whether their VAT number was verified, the amount, the supply date and your return date. It carries the January 2026 standard rate for 15 countries — including the ones that moved, Estonia to 24%, Finland to 25.5%, Slovakia to 23%.
Every check is free, with no key, no limit and nothing watermarked. The $60 key adds the two things a check cannot give you: a .csv of the result for the client file, and reminders 30, 14 and 1 day before the return and EC Sales List dates you enter. For scale, the UK contract-market median for consulting is about £550 a day in 2026.
Questions people ask
What does the Reverse Charge VAT Invoice Checker actually do?
You pick the supply type, your VAT country, your customer's country and whether their VAT number was verified. It returns eight answers: who accounts for the VAT, the VAT to charge, the exact wording for the invoice, the legal basis, the EC Sales List answer, the art. 222 invoice deadline, the money at risk, and the time left to file.
Who is this for?
Bookkeepers, freelancers and agency finance staff raising invoices between UK and EU countries. It fits anyone who issues a handful of cross-border invoices a month and has no in-house VAT specialist - the case where the reverse charge is decided from memory, and the mistake surfaces at the next return rather than at the moment of billing.
Why can a free tool or a chatbot not do this?
A chatbot answers from the rules it was trained on, so it misses the rates that moved in 2026 and it frequently tells a UK supplier to file an EC Sales List, which Great Britain stopped doing after 31 December 2020. It also cannot know whether you verified that VAT number, which is the fact the whole answer turns on.
What is free and what needs the key?
Every check is free, with no key, no limit and nothing watermarked: the decision, the wording, the legal basis, the EC Sales List answer, the deadline and the exposure figure. The key adds two different things - downloading a check as a .csv for the client file, and alarms 30, 14 and 1 day before the dates you enter.
What would this cost if an adviser did it?
The UK contract-market median for consulting work is about GBP 550 a day in 2026, so a single cross-border VAT question put to an adviser rarely comes back under three figures. The other cost is the error itself: HMRC charges up to 30% of the tax for a careless mistake, on top of the tax.
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.